Arif Reshad
University of Essex, UK
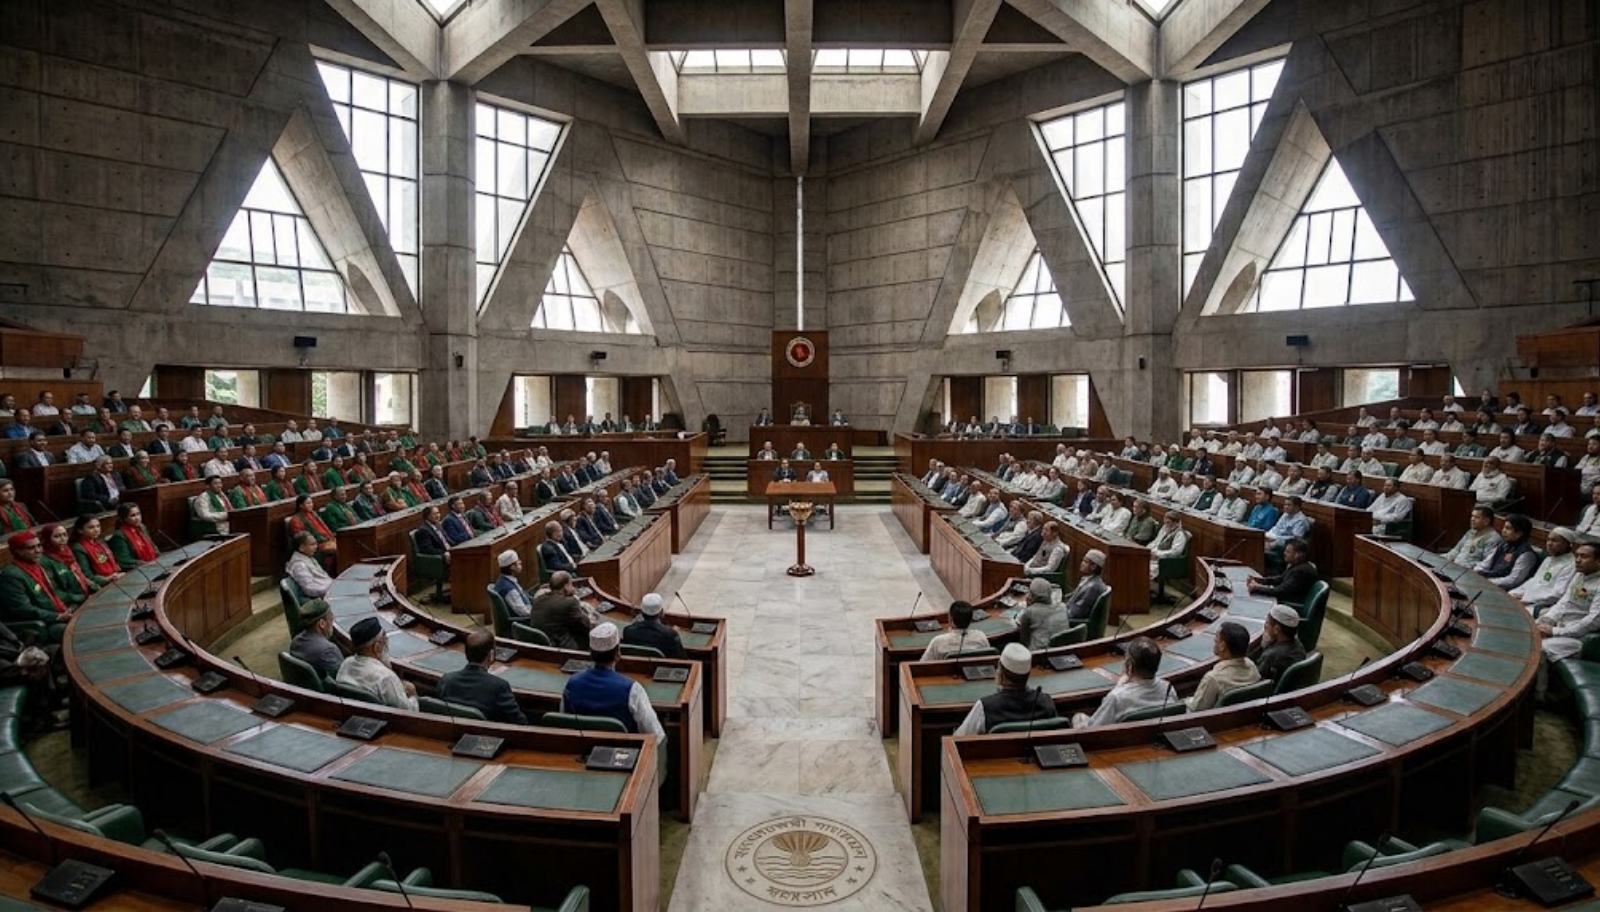
Bangladesh’s gas crisis has become a recurring fixture of Jatiya Sangsad debates in 2026, and the numbers presented by the Ministry of Power, Energy and Mineral Resources deserve a closer, technical look against what the opposition has offered in response. This article presents a technical brief on the accuracy of the proposals.
The Government’s Figures
The government’s case, delivered largely through the power and energy minister, rests on specific and checkable figures. Bangladesh currently produces about 1,630 million cubic feet of natural gas per day from 20 of the 30 gas fields discovered so far. To raise this, the ministry has launched a 150 well drilling and workover programme, of which 30 wells were completed by early September 2026, adding roughly 100 million cubic feet per day to the grid, with a further 85 million cubic feet per day expected once seven more wells finish.
Offshore, an international bidding round covering 26 blocks, 15 deep sea and 11 shallow waters, opened in May 2026 and stays open until November. On imports, the ministry has approved a Chinese backed floating terminal at Maheshkhali that could begin supplying regasified LNG by December 2028, potentially adding 600 million cubic feet per day of import capacity within two years. Politically, officials have offered a phased timeline of partial relief in 2027, more in 2028, and an end to the crisis by 2030.
Testing the Government’s Numbers
Judged purely as engineering and planning statements, these figures are internally coherent and largely traceable to state exploration agency activity reports, which is a reasonable scientific standard for this kind of claim. But two caveats matter.
First, only 30 of the planned 150 wells were finished by the time the 2031 completion target was cited, a completion rate that, if it continues at the same pace, would fall well short of the deadline. Second, offshore exploration in deep and shallow water blocks typically takes several years between discovery and first production, so the 2026 bidding round cannot plausibly close the supply gap before 2030 even in an optimistic scenario.
The Maheshkhali terminal adds import capacity rather than domestic output, and its economics are exposed to exactly the kind of shock the country has just experienced, since the Middle East conflict pushed spot market LNG costs up by an estimated Tk 15,350 crore.
What Regulatory Data Shows
Independent regulatory data complicates the picture further. The energy regulator has put daily gas demand at around 3.8 billion cubic feet against a supply fluctuating between 2.7 and 2.9 billion cubic feet, a shortfall of nearly one billion cubic feet, a gap that includes LNG imports and is therefore wider than the ministry’s domestic production figure alone would suggest. The two data sets are not contradictory once the difference between “domestic production” and “total supply including imports” is accounted for, but the ministry’s parliamentary statements do not always make that distinction explicit, which invites confusion rather than outright inaccuracy.
The Opposition’s Position
Turning to the main opposition party, its parliamentary contributions have tended to focus less on offering a rival production or reserve estimate and more on procedural proposals. These have included suggesting a special taskforce bringing together political parties and technical experts to address the crisis and later offering to place its own technical expert team at the government’s disposal, with party leadership indicating it would have no objection to the government receiving full credit for any resulting solution. Its criticism has centered more on accountability than on geological specifics, pointing to unresolved concerns around so-called ghost billing, the estimated Tk 29,000 crore cost of waiving meter rent entirely, and earlier parliamentary assurances, including on meter and demand charges, that it felt had not been fully honored.
An Asymmetric Comparison
This asymmetry matters for fair comparison. The government offers a quantified, if uncertain, production and import plan checkable against drilling completion rates and bidding outcomes. The opposition has published no competing gas balance or exploration schedule, so there is no genuine clash of technical projections, only a clash between an implementation plan and a governance critique.
Practically, the government’s near-term measures, workover drilling and system loss reduction, are cheaper and faster than new offshore fields, making them the more realistic route to relief before 2028. The opposition’s proposed joint cell could improve coordination and transparency but adds no gas to the grid by itself.
Overall Assessment
On balance, the government’s figures show no major internal contradiction, though its 2030 target rests on assumptions about drilling pace and offshore success that recent progress does not yet support. The opposition’s position, meanwhile, is not scientifically comparable to the ministry’s projections because it is oversight focused rather than data driven, which is itself a notable gap in how the crisis is being debated in parliament.
Reference: