Nishita Shukla
BRAC University
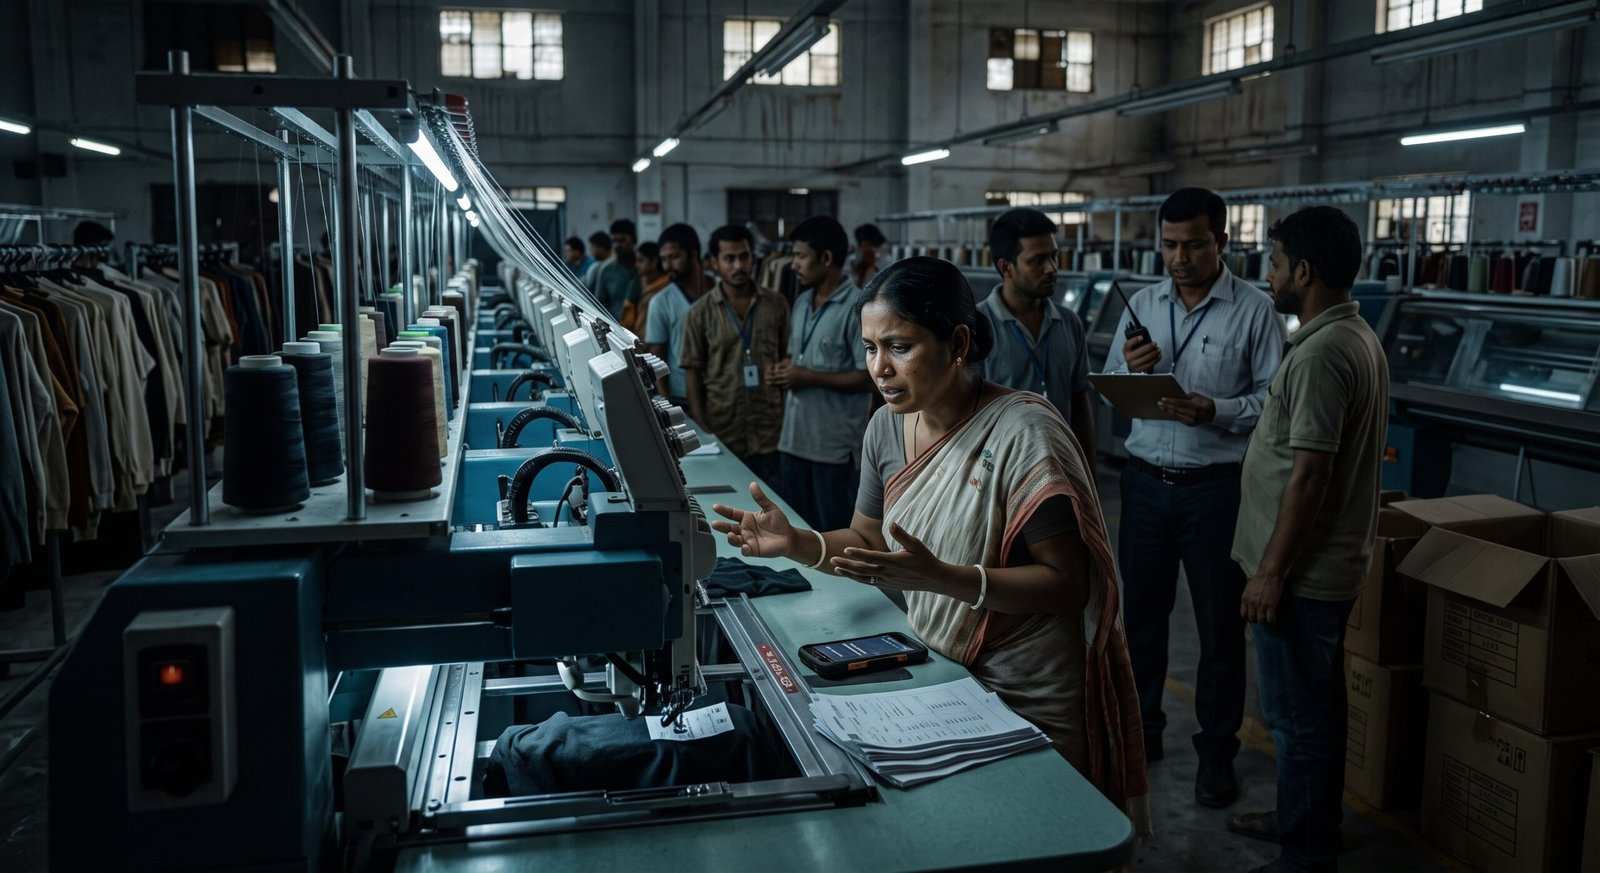
A recent BKMEA survey has surfaced troubling numbers for the country’s knitwear sector: close to fifty five percent of factories polled reported that international buyers had cancelled or scaled back orders due to an ongoing gas and power shortage. The same survey found that about sixty percent of factories had to cut prices just to hold onto buyers, seventy eight percent saw production partially halted, eighty seven percent dealt with shipment delays, and a remarkable ninety two percent absorbed added expenses from sourcing alternative fuel.
Nearly six in ten factories now risk defaulting on bank loans, and roughly seven percent have closed altogether. Taken together, these figures point to something well beyond a passing operational setback. They expose a structural fragility in how Bangladesh secures, and holds onto, its position within global apparel supply chains.
Impact on Foreign Orders
International retailers sourcing from Bangladesh operate on tightly scheduled production calendars aligned with seasonal fashion cycles, which means a missed shipment window carries stakes well beyond delayed revenue. Once a season passes, an entire consignment can become commercially worthless. Buyers facing unreliable delivery tend not to wait it out but to diversify, quietly redirecting a portion of future orders toward alternative sourcing hubs like Vietnam, Cambodia, or India, where energy supply is comparatively steady.
The nearly ninety percent of surveyed factories reporting a risk of eroding buyer confidence precisely reflects this shift already taking hold. Once weakened, a buyer relationship rarely recovers its original volume even after the underlying crisis resolves, since switching costs remain low for buyers operating in a commoditized, price sensitive industry like basic knitwear.
Impact on Local Industry
At home, the crisis deepens the strain on a business model that already runs on thin margins. Bangladesh’s knitwear sector has long competed primarily on cost rather than design innovation or product differentiation, so when factories are forced to pay premium prices for diesel generators or alternative fuel just to keep production running, their already slim cost advantage shrinks further.
The survey’s combination of discounted selling prices, elevated input costs, and wasted labor hours squeezes cash flow at precisely the moment factories most need liquidity to meet delivery commitments. This explains why a large share of respondents now face potential loan default: working capital meant for raw materials or wages is instead being drained by emergency energy costs.
Competition Theory in Context
Bangladesh’s readymade garment sector operates in a market structure close to monopolistic competition at the country level, but the global apparel sourcing market functions much like a contestable market at the supplier country level. Buyers can relatively easily reallocate orders among competing manufacturing hubs offering broadly similar quality and near identical products.
In such a setting, reliability of supply becomes a critical, if underappreciated, dimension of competitiveness alongside price. A country that once competed successfully on low labour costs cannot sustain that advantage if it cannot guarantee consistent production, because buyers will treat unreliable supply as effectively raising the true cost of sourcing from that country, even if the quoted unit price remains low. This is a textbook illustration of how non price factors reshape competitive positioning even in markets that appear to be governed mainly by cost.
The Economics of Incentives
The crisis also lays bare a misalignment of incentives among the parties involved. State owned utilities supplying gas and electricity typically face no direct exposure to the export losses their supply failures cause, creating a moral hazard where the party controlling a critical input bears little of the downstream cost of its own shortcomings. Individual factory owners, meanwhile, have short term incentives to accept whatever orders they can get and quietly absorb rising costs rather than risk permanently losing a buyer, even when doing so threatens their own solvency.
This produces a subtle principal agent problem between factory owners, who deal directly with buyers and carry the reputational risk, and the state apparatus, which controls the energy inputs determining whether those commitments to buyers can actually be honored. Without better alignment, incentives to invest in reliable, factory level backup capacity stay weak, since such investment is expensive and its benefits are partly captured by buyers rather than by the investing firm alone.
Fixing this will require treating energy reliability as a matter of export competitiveness rather than purely domestic utility management, since in a contestable global sourcing market, the real competition is not the factory next door but every other country’s uninterrupted production line.