Iftekhar Rahman
Verdant Global
The Test of Economic Accountability
A decade after President Xi Jinping’s October 2016 visit to Dhaka, Bangladesh faces a more demanding test than the delivery of infrastructure: whether Chinese-backed financing has produced demonstrable public value. Approximately US$24.45 billion in prospective commitments accompanied the visit, elevating bilateral relations and strengthening cooperation under the Belt and Road Initiative. ¹
The central argument is institutional. Without transparent project accounts, credible demand forecasts and independent post-completion reviews, governments cannot reliably distinguish productive investment from expensive construction. The next phase of Bangladesh-China cooperation must be judged by measurable returns, not diplomatic announcements. This requires a distinction between financial performance, wider social benefits and the risks ultimately borne by taxpayers. A project can be socially worthwhile despite charging insufficient user fees; equally impressive construction can conceal poor capital allocation.
Infrastructure and the Utilisation Gap
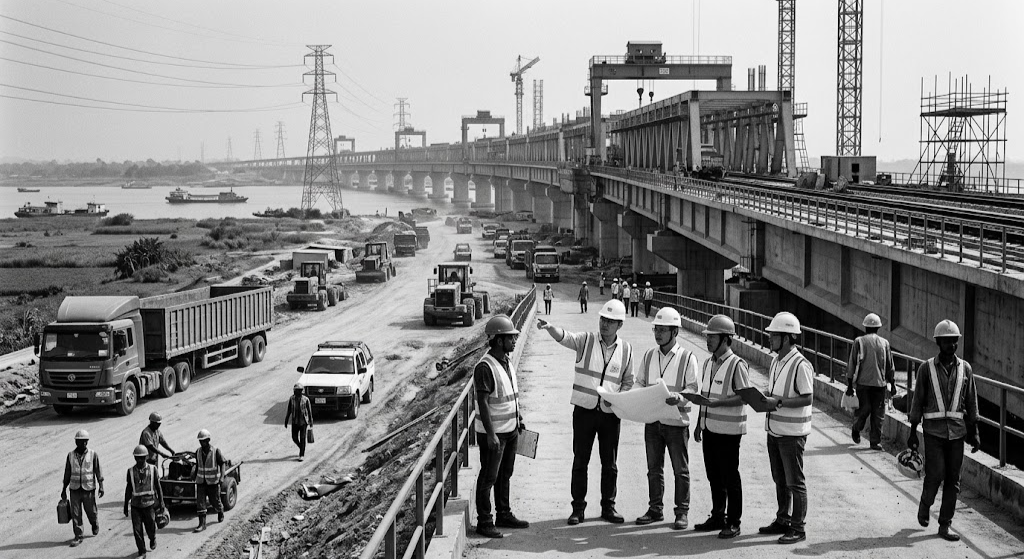
The Padma Bridge Rail Link has improved the physical connection between Dhaka and the southwest. Yet improved access is not synonymous with efficient utilisation. Reporting in May 2026 found that newly constructed railway lines, including the Dhaka-Jashore route, remained underused because of shortages of locomotives and coaches. ² This is evidence of a complementary-investment problem, not proof that the railway lacks long-term value. A credible evaluation would disclose passenger journeys, freight tonnage, train frequency and operating costs against the original appraisal, enabling policymakers to determine whether rolling-stock investment could unlock the line’s potential.
The Karnaphuli River Tunnel offers a more direct financial warning. Parliament was told in June 2026 that average monthly toll receipts were Tk3.37 crore against Tk6.95 crore in operation and maintenance costs. ³ The gap establishes an operating shortfall, not a negative social return: travel-time savings, regional development and future traffic still require independent assessment.
Payra’s coal-fired power station adds a distinct vulnerability. In March 2026, funding pressures and unpaid subsidy arrears threatened coal imports for Payra and Rampal; combined arrears were reported at Tk4,726.37 crore. ⁴ The episode illustrates how generating capacity may coexist with fuel-import and foreign-exchange constraints. None of these examples alone establishes systematic failure, but together they demonstrate why asset delivery must be assessed alongside operational readiness, costs and economic benefits.
Commitments, Disbursements and Debt Risk
The financing record also demands precision. Finance ministry figures reported in June 2026 showed loan agreements for 13 projects worth approximately US$8.89 billion, of which US$5.53 billion had been disbursed by June 2025.⁵ These amounts relate to a particular project pipeline, not the entirety of the 2016 headline commitments. Approval processes in both countries, pandemic disruption and changing lending priorities contributed to delays.
The IMF estimated debt owed to China at US$5.79 billion in FY2025, around 3.1% of Bangladesh’s total public debt; the comparable figure for Japan was US$13.73 billion. ⁶ This does not support portraying China as the dominant sovereign creditor. Nor is the figure an exhaustive measure of every exposure: supplier credits, private commercial obligations and certain project-level liabilities may sit outside the relevant sovereign-creditor category, depending on their classification and guarantees. The IMF ratio should therefore be read as a defined public-debt measure, not as a comprehensive balance sheet of Bangladesh’s entire commercial relationship with China.
The policy risk is therefore less creditor nationality than the interaction of foreign-currency liabilities, uncertain project earnings and weak disclosure. A meaningful audit must reconcile creditor data with guarantees, state-owned enterprise obligations and contractual commitments.
From Construction to Industrial Value
Sovereign loans, engineering contracts and foreign direct investment are economically different. Borrowing leaves repayment obligations with the public sector; well-structured equity investment can shift commercial risk to investors while supporting skills, supplier networks and exports.
The 2026 bilateral communiqué emphasised cooperation in industrial supply chains, export capacity, Mongla Port modernisation and the Chinese Economic and Industrial Zone in Chattogram. ⁷ This presents an opportunity to replace contractor-centred engagement with production-centred partnerships. Bangladesh should prioritise verifiable domestic sourcing, technology absorption and export-linked employment rather than if investment announcements automatically deliver industrial transformation. Agreements should specify skills targets, local supplier participation and export milestones, with independent reporting on whether those promises materialise.
The urgency is heightened by Bangladesh’s scheduled graduation from least-developed-country status on 24 November 2026. Its request for deferral remained under UN consideration in October. ⁸ Whatever the timing, stronger export competitiveness cannot be postponed.
Making Accountability Operational
The Economic Relations Division, working with the Finance Division, should publish a quarterly, project-level register showing commitments, signed loans, disbursements, debt-service schedules, guarantees, completion status and responsible agencies. Commercially sensitive information can be protected without obscuring aggregate public liabilities.
Before approving major borrowing, the Planning Commission should commission independent cost–benefit analysis with realistic demand scenarios, exchange-rate stress tests, environmental costs and comparison against alternative investments. The findings should inform procurement and Cabinet approval rather than follow them.
Finally, the Implementation Monitoring and Evaluation Division should undertake published reviews three and five years after commissioning, reporting utilisation, operating subsidies and realised productivity gains. Project sponsors should explain material deviations and publish corrective plans. These are proposals for institutional practice, not claims that such mechanisms are already in place. Accountability must also extend to Chinese financiers and contractors through scrutiny of lending terms, procurement practices, cost transparency and delivery standards. Public reporting should protect legitimate commercial confidentiality without concealing material risks.
Conclusion
Xi Jinping’s visit helped transform the scale of bilateral cooperation, and several assets offer enduring potential. But neither infrastructure delivery nor a modest share of sovereign debt proves that capital has been allocated effectively. Bangladesh’s next task is to turn financing into demonstrable gains while preserving fiscal flexibility and strategic choice.
The decisive measure of the next decade should be productivity, export growth and independently verified public value, not the size of the next pledge.
References
1. Byron, R. K. and Rahman, M. F. (2016) ‘$24.45b deals’, The Daily Star, 14 October. Available at: https://www.thedailystar.net/frontpage/2445b-deals-1298929.
2. Hasan, R. (2026) ‘BR fails to fully utilise 340km new rail lines set up with Tk55,000cr’, Daily Sun, 17 May. Available at: https://www.daily-sun.com/back-page/875127.
3. Star Online Report (2026) ‘Karnaphuli Tunnel earns Tk 3.37cr, costs Tk 6.95cr a month to operate: Rabiul’, The Daily Star, 29 June. Available at: https://www.thedailystar.net/news/the-parliament-watch/parliament/news/karnaphuli-tunnel-earns-tk-337cr-costs-tk-695cr-month-operate-rabiul-4211316.
4. Kashem, A. (2026) ‘Payra, Rampal won’t supply power in summer unless subsidy payments released’, The Business Standard, 4 March. Available at: https://www.tbsnews.net/bangladesh/payra-rampal-wont-supply-power-summer-unless-subsidy-payments-released-1376701.
5. Byron, R. K. and Chakma, J. (2026) ‘A decade on, half of China’s $20 billion pledge enters aid pipeline’, The Daily Star, 22 June. Available at: https://www.thedailystar.net/spotlight/news/decade-half-chinas-20-billion-pledge-enters-aid-pipeline-4204616.
6. International Monetary Fund (2026) Bangladesh: Debt Sustainability Analysis, IMF Country Report No. 26/024. Available at: https://www.elibrary.imf.org/abstract/journals/002/2026/024/article-A003-en.xml.
7. Ministry of Foreign Affairs of the People’s Republic of China (2026) Joint Communiqué between China and Bangladesh, 26 June. Available at: https://asean.china-mission.gov.cn/eng/zgyw/202606/t20260626_11953170.htm.
8. United Nations Committee for Development Policy (2026) Bangladesh Graduation Status. Available at: https://www.un.org/ldcportal/content/bangladesh-graduation-status.