Sheikh Selim
This editorial review examines the state minister for Fisheries and Livestock pledge of easy term, low interest loans for farmers. It weighs the pledge against alternatives that are financially more sustainable and proposes simpler reforms that could raise productivity without loading rural households with debt.
We do not dismiss the promise. We test it, because the question is not whether farmers need support, which they plainly do, but whether a loan is the best form of it.
What was promised
Speaking at a workshop in Manikganj on implementing the Fish Feed and Animal Feed Act, 2010, the state minister said farmers will receive loans on easy terms at low interest. The aim is to cut production costs and keep eggs, milk and meat affordable. He pointed to grass varieties imported from Australia and to 850 farmers trained to produce cattle feed more cheaply.
At a separate event in Daulatpur he distributed heifers and feed. The intent is welcome, but the detail is thin. No loan size, interest rate, repayment period, lending institution, eligibility rule or budget was named. A promise without this is a sentiment, not a policy.
The case for easy credit, and its limits
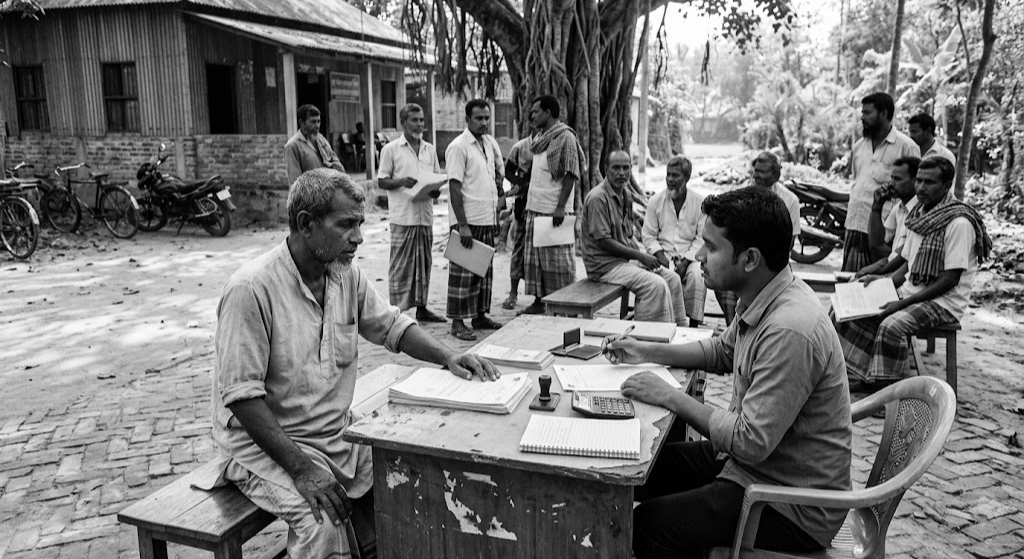
Credit has a legitimate place. Dairy and poultry operators face real upfront costs for animals, sheds, feed stocks, vaccines and equipment. Many cannot self-finance and turn to informal lenders at punishing rates, so cheap formal credit can displace them and let a good farmer expand.
But credit addresses only one constraint, access to cash, and it is rarely the binding one. A farmer who borrows to buy expensive feed, sells milk at a low and unstable price, and loses animals to disease is not made more productive by a loan. He is made more indebted. Credit raises productivity only when the farm’s economics are already working. Where they do not, it magnifies the problem. Our banking system knows this pattern well: loans extended with political enthusiasm and weak appraisal tend to become nonperforming, then rescheduled, then written off, with the cost borne by depositors and taxpayers.
How easy loans can turn into hard debt
Four risks deserve attention. The first is selection. Loans announced as easy attract the connected and already creditworthy, while tenant farmers, women and smallholders without land titles are left out. The second is diversion. Cash is fungible, and part of it drifts to weddings, medical bills or older debts rather than productive assets. The third is repayment mismatch. A dairy animal may take two years to become productive, yet installments often begin within months. The fourth is shocks. Disease, price crashes and floods can wipe out a season, and a defaulter loses access to future credit just when he needs it most.
Low interest carries a quiet cost too. Rates held below the lender’s true cost must be subsidised by someone, and a subsidy that grows with the loan book becomes a fiscal burden. Lenders also ration cheap credit toward safe borrowers, so the intended beneficiaries are often the last to receive it.
Cut the cost, not just finance it
The sounder principle is that a taka saved is better than a taka borrowed. The minister’s own examples point out this way: training farmers to produce cheaper feed and introducing improved grass to lower the cost base permanently, with no debt attached. This work should be scaled far beyond 850 farmers and made the centre of policy, not a footnote to loans.
Feed is the largest cost in dairy, poultry and fish farming, so it deserves more attention than any interest rate. Consider a dairy farmer in Manikganj with three cows. Most of his milk income flows straight to the feed seller, and when prices rise or bags turn out lighter than labelled, his margin vanishes before he repays a single instalment. A loan simply lets him buy the same expensive feed on credit. Community fodder cultivation on fallow and char land, with seeds and cuttings supplied at cost, would give him a cheap green source nearby. Farmer groups producing silage and mixed rations collectively could cut costs further by pooling labour, storage and bulk purchases.
The state has its own part to play. The Feed Act must be enforced firmly, because adulterated or underweight feed is a hidden tax on farmers, and quality testing at mills and markets protects margins better than an interest rate cut. When domestic supply runs short, easing duties and market frictions on feed ingredients would prevent shortages from becoming price shocks at the farm gate. A farmer whose feed bill falls even modestly can repay a small loan comfortably, or may not need one at all, which shows a policy is strengthening farms rather than merely financing them.
Price and market certainty
Productivity rises when farmers trust that extra output will fetch a fair price. Too often a good season brings a price collapse, and farmers learn to hold back. Three measures would help.
- Milk collection and chilling centres run by cooperatives or processors, with transparent pricing and prompt payment, so farmers are not at the mercy of middlemen.
- Contract farming, in which a processor commits in advance to buy at an agreed formula. A signed purchase agreement is also something a bank can lend against.
- A modest price stabilisation mechanism for milk and eggs in surplus periods, supported by government procurement for school meals and public institutions. This creates steady demand and nutritional benefit together.
Insurance and animal health
Risk is what turns loans into defaults. Livestock and poultry insurance, linked to vaccination records and measurable triggers such as disease outbreaks or extreme weather, would protect farmers from the shocks that destroy repayment. Index based products pay out on a verifiable event rather than a lengthy claims process, so they are cheaper to run and harder to abuse. Premium support for smallholders is likely to cost less overtime than repeated loan rescheduling.
Routine animal health matters just as much. Vaccination and deworming delivered through trained community health workers cost little and prevent losses no loan can reverse. Subsidised artificial insemination with quality semen lifts milk yield per animal, which is the most direct route to productivity. These are services the state is well placed to provide.
Rewarding performance
If the government wants to put money in farmers’ hands, a performance linked matching grant is a better instrument than a loan. A farmer who vaccinates, keeps records, meets feed quality standards and raises yield could receive a partial grant toward the next asset, such as a share of a heifer’s cost or a milking machine. This rewards effort carries no repayment burden and gives a visible incentive to improve. It also lets officials give direct support to those who show results rather than those with the best connections. Recognition for top performing farmer groups can add motivation at little cost.
If loans remain, reform them
We do not argue that loans should vanish. We argue they should be auxiliary and carefully designed. Picture a woman in Daulatpur offered a loan to buy a heifer. If the money arrives as a lump sum, it is easily pulled toward a medical bill, a wedding or an old debt, and the heifer is never bought. If the loan goes directly to the supplier, tied to the asset itself, the animal reaches her shed and the loan serves its purpose.
Repayment should follow the rhythm of her farm rather than the bank’s calendar. A heifer takes time to mature and begin giving milk, so a grace period is realistic, and installments deducted from milk sales through a cooperative would let her repay as she earns.
Risk should also be shared more fairly. A credit guarantee fund would let banks lend to smallholders without pushing every taka of risk onto the borrower, and group lending through cooperatives adds peer accountability. Digital records of loans, sales and animal health would let lenders judge her on actual performance rather than connections or collateral and reward the discipline she has built.
Finally, a transparent public register of beneficiaries would make the programme accountable, so citizens can see who receives support. Designed this way, a loan strengthens a working farm instead of burdening a fragile one.
Verdict
Our suggested sequence is plain. First, lower the cost base through feed, fodder and quality enforcement. Second, secure markets and prices through collection centres, contracts and procurement. Third, reduce risk through insurance, vaccination and breeding services. Fourth, reward results with matching grants. Only then should credit follow, in modest, well-designed form, for farmers whose enterprises are ready to grow. This builds farms that can repay, instead of lending them to farms that cannot.
The minister is right that farmers and consumers both suffer when production costs are high. But easy loans treat the symptom of thin cash while leaving untouched the causes: expensive feed, unstable prices and unmanaged risk. Without detail, safeguards and complementary reforms, the promise risks becoming another cycle of cheap credit, weak repayment and quiet write offs.
The better path is to make farming profitable first and let credit follow profitability. We urge the ministry to publish the terms of its proposed scheme, to expand the feed and food it has begun, and to place cost reduction, market access and risk protection at the heart of its agenda. Farmers do not need to be indebted to productivity. They need a system in which productivity pays.